Fed Rate Decision September 2026: What to Watch
Comes out: Tuesday, September 1, 2026 at 2:00 p.m. ET
Published by: Federal Reserve
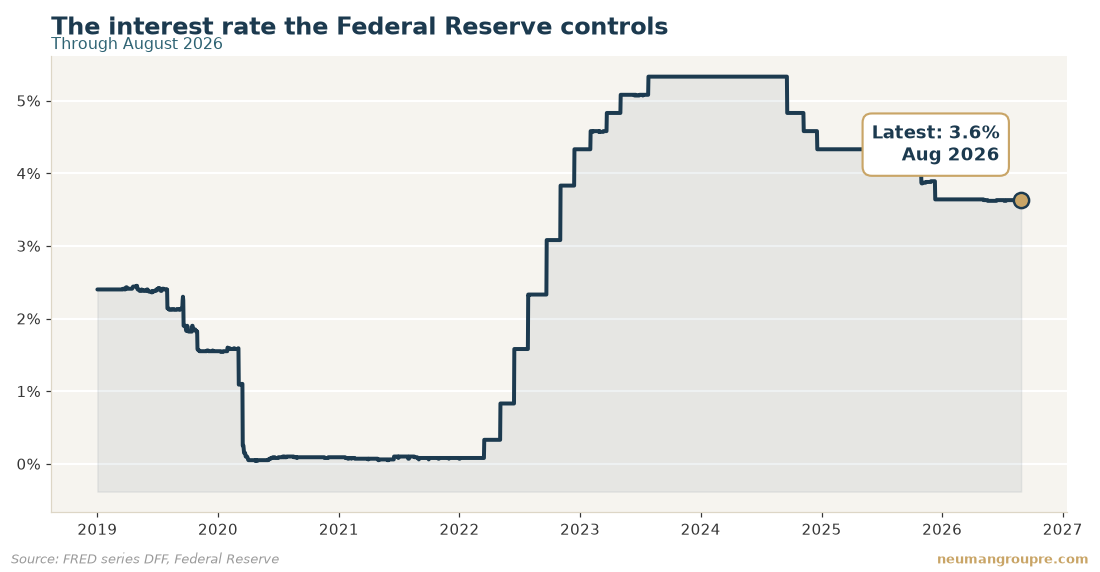
Fed's key rate holds at 3.6% in August 2026
The Federal Reserve is the group that guides money and interest rates for the whole country. It just held the interest rate it controls at 3.6% for August 2026. That rate was also 3.6% last time, so it did not move.
A year ago that same rate was 4.3%. So over the past year it has come down. But right now it is flat, meaning it stayed the same.
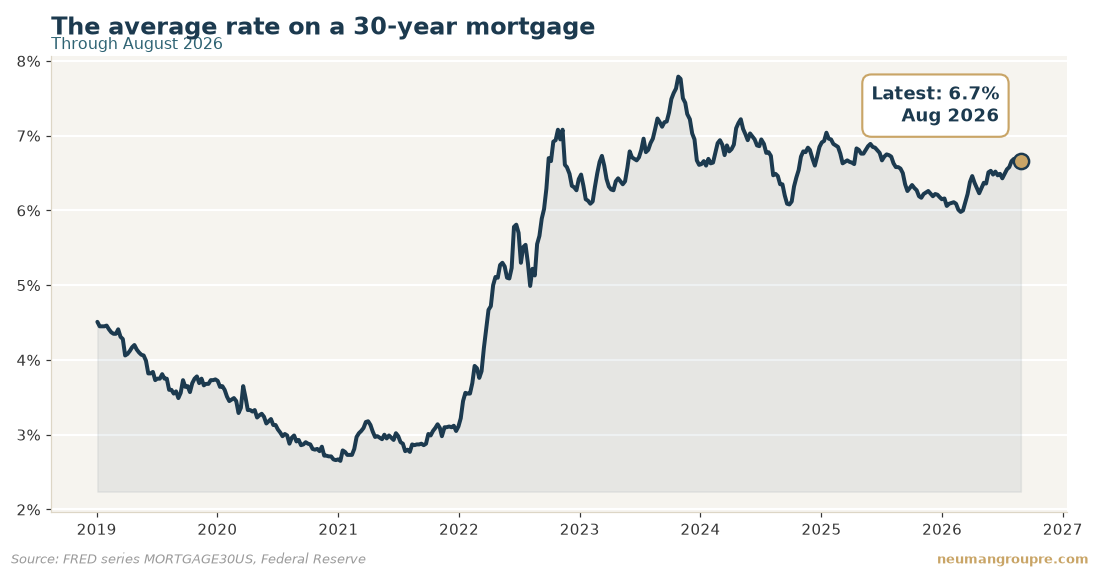
The Fed does not set your mortgage rate. It sets the mood. What the Fed says about the future often moves mortgage rates that same day. Today the average rate on a 30-year mortgage is 6.7%.
Here is what 6.7% looks like on a $600,000 home loan. The monthly payment for just the loan itself would be about $3,870, before taxes and insurance. A small change in the rate can change that payment by a lot over 30 years.
What it means for you in South Florida:
- Buyers: Rates held steady, so your payment math today is close to last month. You can plan without a sudden jump.
- Owners and sellers: Steady rates keep buyers in the market, which supports what your home can sell for.
- Renters thinking of buying: Nothing changed this month, so you have time to run the numbers and get ready.
On Tuesday, September 1, 2026, at 2:00 p.m. Eastern time, the Federal Reserve will share its next rate decision. The Federal Reserve is the group that guides money and interest rates in the United States. Most people call it the Fed.
You may be searching for the fed rate decision, the fomc meeting today, or whether the Fed will cut rates. This page explains what is coming and why it matters.
Here is why a normal person should care. The Fed does not set your home loan rate. But what it says can move mortgage rates the same day. That changes what you pay to buy, sell, or rent a home in South Florida.
What the Fed does on Tuesday
The report coming out is called the FOMC statement. It tells you if the Fed is raising, lowering, or holding its main interest rate. It also tells you how the Fed feels about the months ahead.
What this report measures
The Fed controls one rate. It is called the Federal Funds Rate. This is the rate banks charge each other to borrow money overnight. When that rate goes up, borrowing gets more costly across the whole economy. When it goes down, borrowing gets cheaper. Over time that reaches car loans, credit cards, and home loans.
What the charts show right now
The chart above shows the Fed's main rate sitting at 3.6% in August 2026. That is about the same as the month before. A year ago it was 4.3%. So over the past year, the Fed's rate has come down.
The second chart shows the average rate on a 30-year mortgage. A 30-year mortgage is a home loan you pay back over 30 years. That average sits at 6.7% in August 2026. That is about the same as the month before. A year ago it was 6.5%. So even though the Fed's rate fell over the year, mortgage rates went up a little. This surprises many people. It shows the Fed does not pull the mortgage string directly.
Why the words matter more than the number
Sometimes the rate does not change, but the market still moves. That is because traders listen to what the Fed says about the future. If the Fed hints more cuts are coming, mortgage rates can drop before the Fed acts. If it hints rates will stay high, mortgage rates can climb. So read the message, not just the number.
What it means for your mortgage payment
Your monthly payment depends on your rate. On a $600,000 loan, the gap between 6.5% and 6.7% is real money every month. A higher rate means a bigger payment. A lower rate means a smaller one. If the Fed sounds worried about rising prices tomorrow, rates could tick up. If it sounds calm, rates could ease.
What it means for home prices in South Florida
When rates rise, monthly payments rise. Some buyers then step back. That can cool prices. When rates fall, payments shrink, and more buyers can afford to shop. That can hold prices up. In Miami-Dade, Broward, and Palm Beach, this push and pull shapes how fast homes sell.
What it means for rent
Rent and rates are linked too. When home loans cost more, some people stay renters longer. That keeps demand for rentals strong. If you own a place and rent it out, your own loan cost matters as well. A higher rate on your loan eats into what you keep each month.
Talk it through before you act
You do not need to guess tomorrow's number. You just need a plan for each case. The Neuman Group works across Miami-Dade, Broward, and Palm Beach. If you are buying, selling, or renting out a home, call us at 954-228-5001. We can walk you through what a rate move means for your budget.
Three things to watch
Questions people ask
Will the Fed cut rates on September 1, 2026?
Nobody knows the number until 2:00 p.m. Eastern time that day. The Fed could raise, lower, or hold its main rate. This page explains what each choice would mean for you.
Does the Fed set my mortgage rate?
No. The Fed sets its own short-term rate, which is 3.6% as of August 2026. Mortgage rates move on their own, though the Fed's words often push them the same day.
Why did mortgage rates go up while the Fed's rate went down?
Over the past year the Fed's rate fell from 4.3% to 3.6%. But the average 30-year mortgage rose from 6.5% to 6.7%. The two rates do not always move together, because the mortgage market watches many things at once.
Should I wait to buy until rates drop?
That is a personal call. Waiting could help if rates fall, but prices and homes for sale can change too. It helps to run the numbers on a real home before you decide.
What does this mean if I rent out a property?
Your own loan cost shapes what you keep each month. If rates stay high, some people rent longer, which can keep demand for rentals strong. A move in rates changes both sides of that math.
Every figure on this page comes straight from FRED (Federal Reserve Economic Data, Federal Reserve Bank of St. Louis) — series DFF, MORTGAGE30US. We publish these before the report lands so you can read the background while it is still quiet, then we add the actual number here the moment it is out.
Call 954-228-5001 or ask us for a free read on your property.