Mortgage Rates Today: Freddie Mac Report, August 2026
Comes out: Thursday, August 27, 2026 at 12:00 p.m. ET
Published by: Freddie Mac
30-year mortgage holds at 6.7% this week
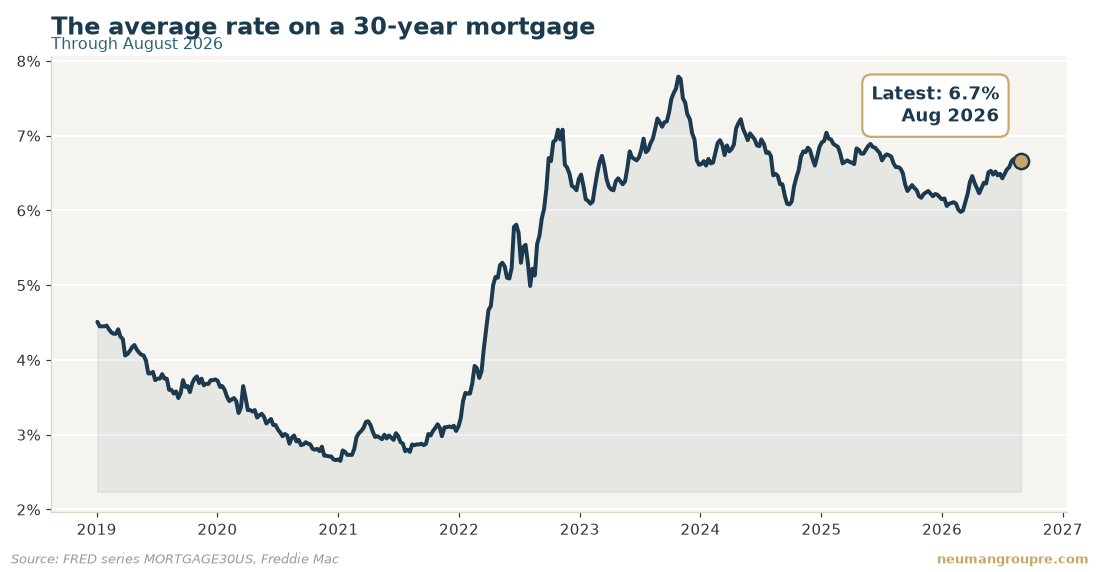
The average rate on a 30-year mortgage is 6.7%. That is the number most buyers use when they borrow to buy a home. It comes from a weekly report by Freddie Mac, a company backed by the government that helps fund home loans.
This is about the same as last time, when the rate was also 6.7%. So week to week, almost nothing changed.
A year ago the rate was 6.5%. That means rates are a little up from where they were last summer. It is a small move, but on a big loan even a small move adds to what you pay each month for thirty years.
Here is why it matters. On a $600,000 loan, the rate is what sets your monthly payment. A lower rate means a lower payment. A higher rate means a higher payment. Right now that number is holding steady, so your payment math this week looks a lot like last week.
What this means for South Florida: if you are buying, a flat rate gives you time to shop without the target moving on you. If you are selling, buyers are working with steady payment math, so price it right for today. If you already own, there is no big rate swing to react to this week.
A new mortgage rate report comes out this Thursday, August 27, 2026, at 12:00 p.m. Eastern time. It is called the Primary Mortgage Market Survey, and Freddie Mac puts it out every week. It tells you the average rate on a home loan right now.
This is the number that decides your monthly payment. When the rate moves, the amount you owe each month moves with it. That is true whether you are buying, selling, or already paying a mortgage.
We wrote this before the new number came out. That way, when you search for it, you already know what it means and what to do next.
What this report actually measures
The Primary Mortgage Market Survey is a weekly average. Freddie Mac, a large company that helps fund home loans, asks lenders across the country what rate they are charging. Then it reports the average. The one most people watch is the 30-year fixed rate. Fixed means the rate stays the same for the whole loan. Thirty years is how long you have to pay it back.
This report does not set your exact rate. Your own rate depends on your credit, your down payment, and the lender you pick. But the average is a strong signal. When it goes up, most people's offers go up too. When it goes down, most people's offers go down.
What the charts show right now
The chart above shows the average 30-year mortgage rate. Right now it sits at 6.7% for August 2026. That is about the same as last time, which was also 6.7%. A year ago it was 6.5%, so the rate is up a little from where it was twelve months back.
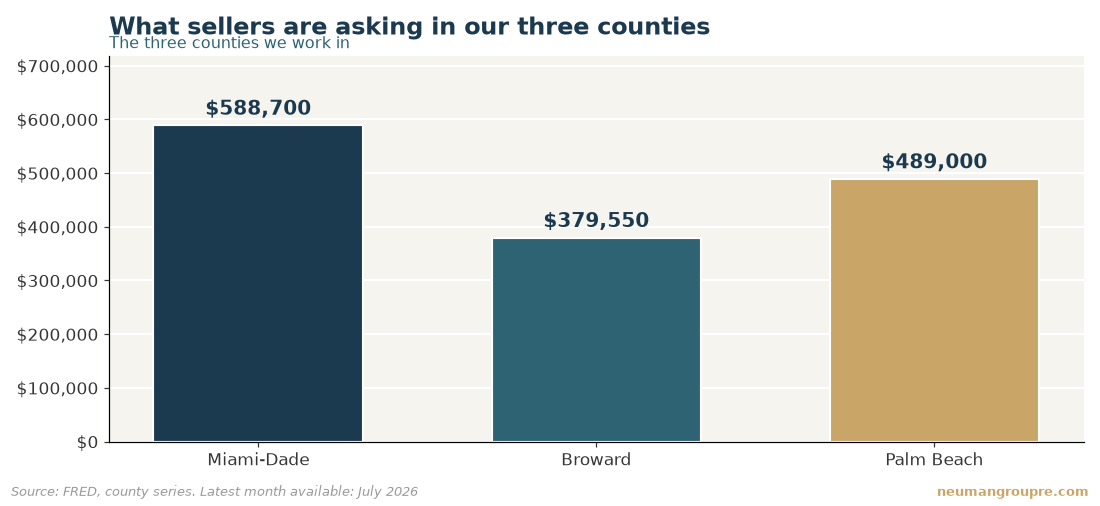
The chart of local asking prices tells a different story. Asking price means what sellers are listing their homes for, not what they finally sell for. In July 2026, the typical asking price was $588,700 in Miami-Dade, $379,550 in Broward, and $489,000 in Palm Beach. All three counties are down from a year ago. Miami-Dade was $600,000, Broward was $408,275, and Palm Beach was $495,000.
What it means for your monthly payment
Rates and prices pull in different directions here. Asking prices in our three counties have come down over the year. But rates are a touch higher than a year ago. A small move in the rate is real money on a big loan. On a $600,000 loan, half a point changes your payment every single month for thirty years. So watch the rate closely if you are shopping.
What it means for home prices
When rates go up, monthly payments go up, and fewer people can afford to buy. That tends to cool prices over time. When rates go down, buying gets cheaper, more people jump in, and prices often firm up. The local price drops you see in the chart above happened while rates stayed near this level. If rates fall from here, that downward price trend could slow or reverse.
What it means for rent in South Florida
Rent and mortgage rates are linked. When high rates keep would-be buyers renting longer, demand for rentals stays strong. If you own a place and rent it out, that can support the rent you charge. If rates fall and more renters become buyers, rental demand can soften. Nothing changes overnight, but the direction of the rate is a clue to where rents drift next.
The bottom line
You cannot control the rate. You can control your timing and your budget. Know what a monthly payment looks like at today's 6.7% before you shop, and keep an eye on Thursday's number.
Three things to watch
What sellers are asking in our three counties
| County | Now | A year ago | Direction |
|---|---|---|---|
| Miami-Dade | $588,700 | $600,000 | down |
| Broward | $379,550 | $408,275 | down |
| Palm Beach | $489,000 | $495,000 | down |
County figures from FRED, latest month published: July 2026.
Questions people ask
What are mortgage rates today?
As of August 2026, the average 30-year fixed mortgage rate is 6.7%. That is about the same as the prior reading and up from 6.5% a year ago. A fresh weekly number comes out Thursday, August 27, 2026, at noon Eastern time.
Who publishes the weekly mortgage rate report?
Freddie Mac publishes it. It is called the Primary Mortgage Market Survey. Freddie Mac asks lenders across the country what rate they are charging and reports the average each week.
Will my own rate match the average?
Not exactly. The average is a national snapshot. Your rate depends on your credit, your down payment, the loan type, and the lender. The average tells you which way the market is moving.
Why does the mortgage rate matter so much?
It sets your monthly payment. On a $600,000 loan, even half a point is real money every month for thirty years. A higher rate means a bigger payment for the same home.
Are South Florida home prices going up or down?
Asking prices are down from a year ago in all three counties. In July 2026 the typical asking price was $588,700 in Miami-Dade, $379,550 in Broward, and $489,000 in Palm Beach. Asking price is what sellers list at, not the final sale price.
Every figure on this page comes straight from FRED (Federal Reserve Economic Data, Federal Reserve Bank of St. Louis) — series MORTGAGE30US. We publish these before the report lands so you can read the background while it is still quiet, then we add the actual number here the moment it is out.
Call 954-228-5001 or ask us for a free read on your property.